
How to Reduce Corporation Tax: 10 Effective Tax-Saving Tips
 Team Nomi
6 minutes read
Corporation tax is one of the biggest tax expenses for many UK limited companies. While paying tax is a normal part of running a business, there are several legal ways to reduce the amount you owe.
Understanding how to reduce corporation tax can help improve cash flow, increase profits, and leave more money available for business growth. The key is effective corporation tax planning throughout the year rather than waiting until the filing deadline approaches.
In this blog, we explain practical ways to reduce your corporation tax bill while staying fully compliant with HMRC rules.
Claim All Allowable Business Expenses
One of the simplest ways to reduce taxable profits is to claim every legitimate business expense.
Allowable expenses can include:
-
- Office rent
- Utility bills
- Business insurance
- Professional fees
- Staff salaries
- Travel costs
- Marketing expenses
- Software subscriptions
If an expense is wholly and exclusively for business purposes, it may be deductible from your profits before corporation tax is calculated.
Keeping accurate records throughout the year makes it easier to identify all allowable expenses.
Invest in Equipment and Business Assets
Purchasing equipment for your business can reduce taxable profits through capital allowances.
Examples include:
-
- Computers and laptops
- Office furniture
- Machinery
- Business vehicles
- Tools and equipment
These investments can often qualify for valuable corporation tax relief, helping businesses lower their overall tax bill while supporting growth.
Use the Annual Investment Allowance (AIA)
The Annual Investment Allowance allows businesses to deduct the full cost of qualifying equipment purchases from taxable profits up to the applicable annual limit.
This can provide significant tax savings for companies investing in business assets.
Examples of qualifying purchases may include:
| Qualifying Assets | Examples |
| Office Equipment | Computers, desks, printers |
| Machinery | Manufacturing equipment |
| Tools | Trade and construction tools |
| Fixtures | Lighting, shelving, fittings |
Planning asset purchases carefully can help maximise available tax relief.
Claim Research and Development (R&D) Relief
Many companies do not realise they may qualify for Research and Development (R&D) tax relief.
R&D activities can include:
-
- Developing new products
- Improving existing products
- Creating innovative software
- Solving technical challenges
If your company carries out qualifying activities, you may be able to reduce your corporation tax bill significantly through R&D corporation tax relief.
Because eligibility rules can be complex, professional advice is often recommended.
Make Employer Pension Contributions
Employer pension contributions are generally treated as an allowable business expense.
Benefits include:
-
- Reduced taxable profits
- Increased retirement savings
- Potential tax efficiency for directors
For many owner-managed businesses, pension contributions can be an effective corporation tax planning strategy.
Use Trivial Benefits and Employee Benefits
Certain employee benefits can provide tax-efficient rewards while helping manage company profits.
Examples may include:
-
- Small gifts
- Seasonal vouchers
- Staff welfare benefits
Where HMRC rules are met, these benefits can be provided without creating significant tax liabilities.
Always check current HMRC guidance before implementing benefit schemes.
Donate to Charity
Charitable donations made by limited companies to qualifying charities are usually deductible for corporation tax purposes.
Benefits include:
-
- Supporting charitable causes
- Reducing taxable profits
- Demonstrating corporate social responsibility
Donations must generally be made to recognised charities to qualify.
Offset Trading Losses
If your company experiences losses, those losses may be used to reduce future taxable profits.
Depending on circumstances, losses may be
-
- Carried forward
- Carried back
- Offset against other qualifying profits
Proper use of loss relief can play an important role in long-term corporate tax management.
Review Director Salary and Dividends
The balance between director salary and dividends can affect overall tax efficiency.
Many business owners choose a combination of:
-
- Salary
- Dividends
- Pension contributions
The most suitable structure depends on individual circumstances and current tax rules.
Regular reviews can help ensure tax efficiency while remaining compliant.
Claim Capital Allowances
Capital allowances allow businesses to claim tax relief on qualifying capital expenditures.
Common qualifying assets include:
-
- Plant and machinery
- Equipment
- Fixtures
- Certain building improvements
Businesses that fail to claim capital allowances may end up paying more corporation tax than necessary.
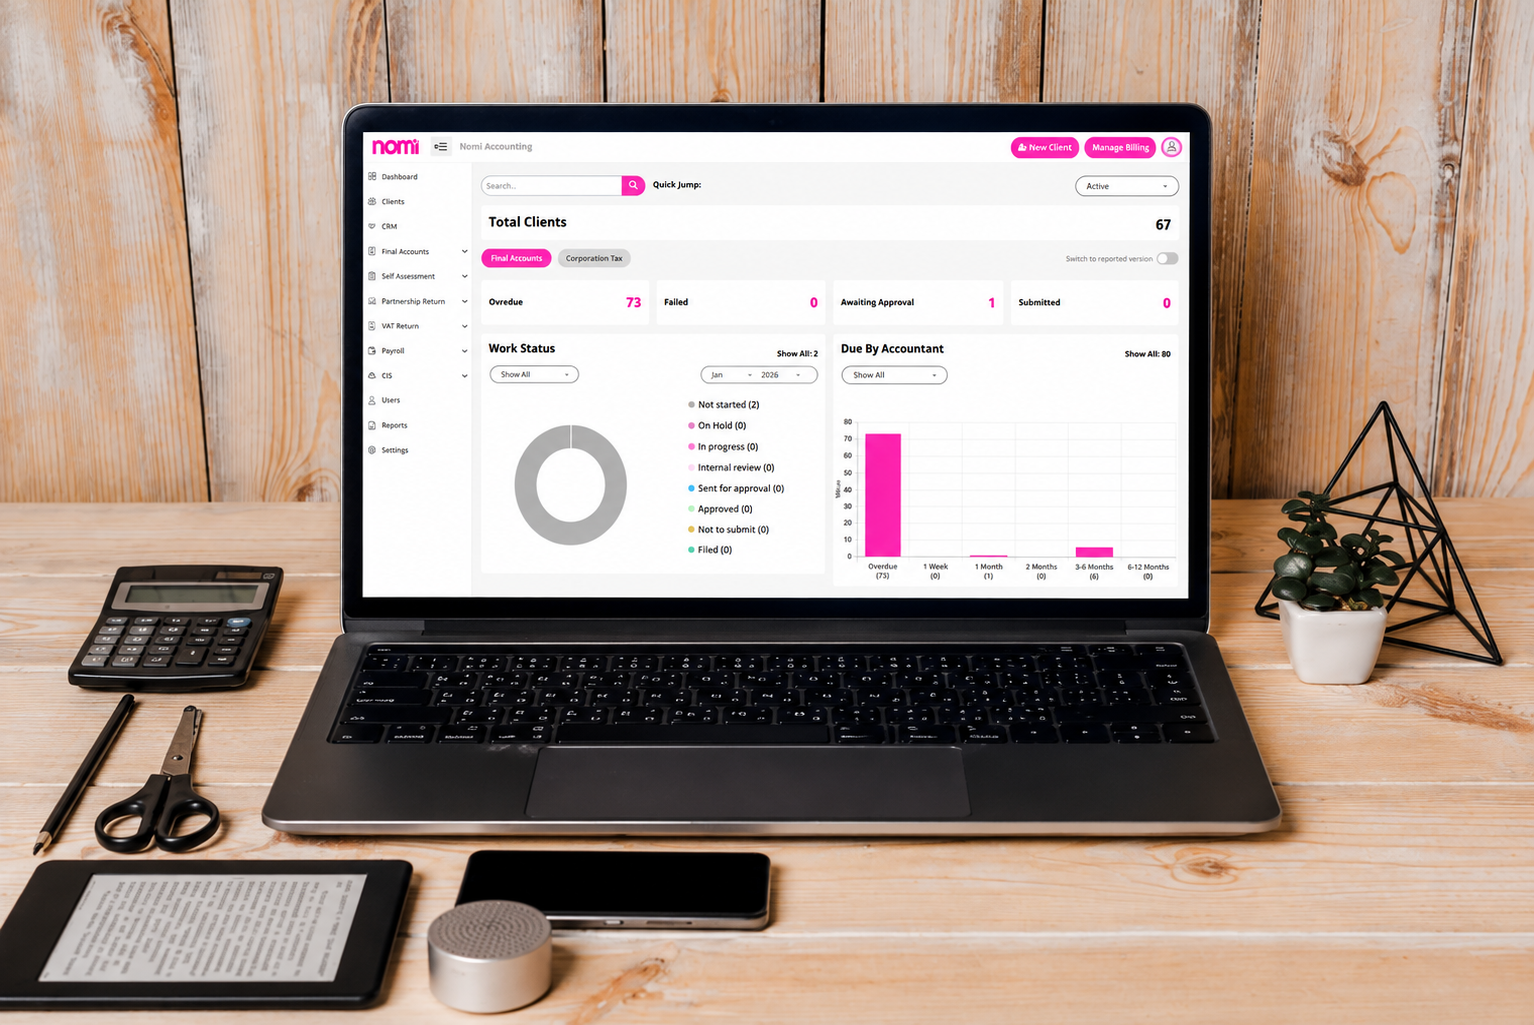
For accountants and bookkeepers seeking an efficient corporation tax solution, Nomi offers a cloud-based platform that simplifies final accounts and corporation tax compliance.
Nomi Corporation Tax Software helps firms
-
- Prepare and file corporation tax returns
- Create final accounts
- Manage multiple clients from one platform
- Maintain compliance with HMRC requirements
- Reduce manual administration
The software is particularly useful for practices looking for a smooth approach to corporate tax management while improving efficiency and accuracy.
By combining final accounts production and corporation tax functionality in a single platform, Nomi helps accountants spend less time on administration and more time supporting clients.
Conclusion
Learning how to reduce corporation tax starts with understanding the reliefs, deductions, and planning opportunities available to your business. From claiming allowable expenses and capital allowances to making pension contributions and using available corporation tax relief, there are many legitimate ways to lower your tax bill.
Successful corporation tax planning is not about avoiding tax; it is about ensuring your business only pays what it legally owes. By reviewing your finances regularly, maintaining accurate records, and using reliable corporation tax software businesses can improve compliance, increase efficiency, and achieve better corporate tax management throughout the year.
Disclaimer: This blog is intended for general informational purposes only and should not be considered accounting, tax, or financial advice.Readers should consult a qualified accountant or tax professional before making any tax-related decisions. Always refer to the latest HMRC guidance for current regulations and requirements.
Frequently Asked Questions
- When should I start planning to reduce my corporation tax bill?
Ans: It is best to start corporation tax planning throughout the financial year rather than waiting until the filing deadline. - Can poor bookkeeping increase my corporation tax liability?
Ans: Yes, inaccurate or incomplete records can result in missed expense claims and higher corporation tax payments. - Can I amend a corporation tax return if I missed a tax relief claim?
Ans: Yes, companies can usually amend a corporation tax return within the allowed HMRC time limits. - What happens if I pay corporation tax late?
Ans: HMRC may charge interest and penalties on late corporation tax payments, increasing the overall amount owed. - How can corporation tax software help reduce errors in tax returns?
Ans: Corporation tax software automates calculations, improves record accuracy, and helps ensure returns are completed correctly and on time.
Want to find out more?
Book a free 30-day trial and see how our accounting software can help you manage staff, increase profitability and take your practice to the next level.
How to Apply for VAT Exemption in the UK
To apply for VAT exemption in the UK, your business must meet HMRC’s conditions and...
Read More
What accountants should actually look for in practice management software
As an accounting practice grows, managing the work around accounting can become as challenging as...
Read More
How AML software helps accountants in accounting practices
Anti-money laundering (AML) checks are an important part of running an accounting practice in the...
Read More

Making Tax Digital for Accountants: A Practical Guide for 2026/27
Making Tax Digital (MTD) for Income Tax is now live. Since 6 April 2026, sole...
Read More